Are you cruising through the scenic lanes of Massachusetts wondering about the cost of keeping your ride insured? You’re not alone! Navigating the world of auto insurance can be as tricky as Boston’s one-way streets. But fear not, we’ve got the roadmap to help you understand the ins and outs of auto insurance in the Bay State.
In this guide, we’ll steer you through the essential types of coverage, the mandatory requirements, and the variables that influence those pesky premium rates. So buckle up and let’s drive through the details of how much auto insurance truly costs in Massachusetts!
Overview of Auto Insurance in Massachusetts
Massachusetts auto insurance is a mix of required coverages and optional add-ons that protect you and your vehicle. But how much do you really need to get on the road legally?
There are several basic types of auto insurance coverage available in Massachusetts. At the core, you’re looking at liability insurance to cover bodily injury and property damage. Then there’s personal injury protection (PIP) and uninsured motorist coverage, which are also part of the state’s minimum requirements.
Required Minimum Coverage Limits
In Massachusetts, there are specific minimum coverage limits you need to meet. Here’s the deal: you must have at least $20,000 per person and $40,000 per accident for bodily injury (BI), and $5,000 for property damage (PD). PLUS, a $8,000 limit for PIP.
If you’re caught without these minimums, you could face hefty fines or even lose your license. So it’s crucial to make sure your policy meets these standards.
Factors Influencing Auto Insurance Rates
Wondering why your rates might be sky-high? Several factors play a role in calculating auto insurance rates in Massachusetts. Your driving record is a biggie; accidents and violations can spike premiums. Then there’s your zip code, which insurers use to gauge risk based on local accident rates and theft statistics.
Pro Tip: Keep a clean driving record and consider bundling your auto insurance with other policies to snag some discounts.
Cost Factors in Massachusetts Auto Insurance
Did you know that the average auto insurance premium in Massachusetts is higher than the national average? That’s right, BUT there’s more to the story than just numbers. Let’s dive into the specific factors that influence these costs.
Auto insurance premiums aren’t just a roll of the dice. They’re determined by a variety of factors unique to each driver and location. In Massachusetts, these factors include your driving record, the coverage you choose, and even where you live within the state.
Location’s Impact on Insurance Cost
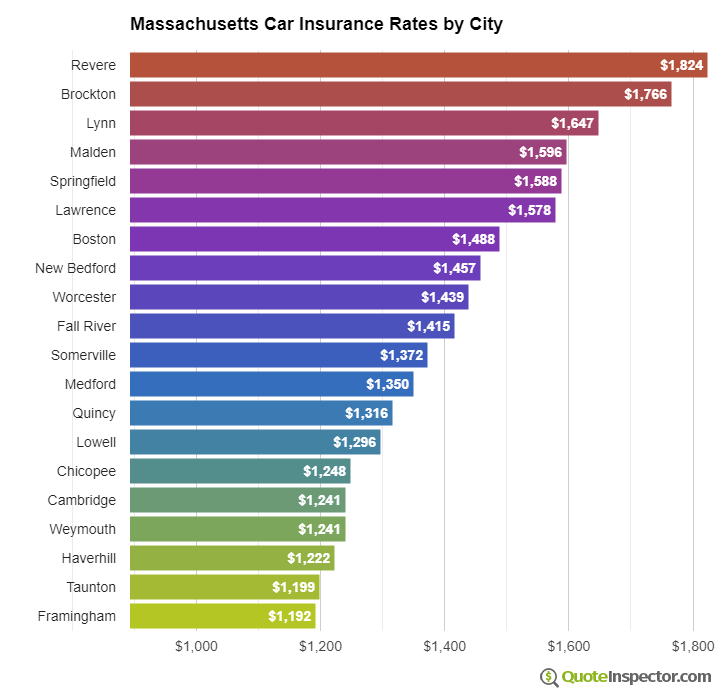
Your location within Massachusetts can significantly affect your insurance rates. Urban areas like Boston tend to have higher premiums due to increased traffic and accident rates. Meanwhile, rural areas might offer lower premiums. BUT, it’s not just about the city. Other factors like crime rates and local weather conditions also play a role.
| City | Average Premium | Factors Affecting Costs | Typical Discounts |
|---|---|---|---|
| Boston | $1,500 | High traffic, accident rates, theft | Multi-policy, safe driver |
| Springfield | $1,200 | Moderate traffic, theft rates | Good student, defensive driving |
| Amherst | $900 | Low traffic, low accident rates | Multi-car, loyalty |
Driving History’s Role in Premium Rates
Your driving history is like your insurance report card. A clean record can reward you with lower premiums, while a history with accidents or violations can make your rates skyrocket. Here is the deal: insurers see your past behavior as an indicator of future risk.
So, if you’ve had a few speeding tickets or a fender bender (or two), expect your premium to reflect that. BUT, there’s hope! Many insurance companies in Massachusetts offer programs to help you manage your rates.
Pro Tip: Want to lower your rates? Consider taking a defensive driving course. It can not only improve your skills but often comes with a discount on your premium.
Average Auto Insurance Costs in Massachusetts
How much are you really paying for auto insurance in Massachusetts? It’s more than you might think. The average cost can vary wildly depending on your profile and the vehicle you drive.
Let’s take a deep dive into the numbers. On average, Massachusetts drivers are shelling out around $1,400 annually for their car insurance. But here is the deal: your actual premium can be higher or lower based on several key factors like your age, driving experience, and even your choice of insurer.
Understanding the Impact of Age and Experience on Insurance Premiums
Age is more than just a number when it comes to car insurance. Younger drivers, especially those under 25, often see premiums as high as $3,000 annually due to higher risk factors. The longer you’ve had your license, the more you benefit from lower rates.
Check out this table to see how different driver profiles compare:
| Driver Profile | Average Annual Premium | Insurance Provider | Discounts Available |
|---|---|---|---|
| Young Driver (Under 25) | $3,000 | Provider A | Good Student, Safe Driver |
| Experienced Driver (Over 25) | $1,200 | Provider B | Multi-Policy, Loyalty |
| Senior Driver (Over 65) | $1,100 | Provider C | Defensive Driving, Low Mileage |
Pro Tip:
Always ask about discounts. You could save hundreds.
Whether it’s bundling with home insurance or maintaining a clean driving record, discounts can significantly cut down your insurance costs.
Comparison of Insurance Providers in Massachusetts
Wondering which auto insurance company to choose in Massachusetts? You’re not alone. The market is packed with options, and picking the right one can save you big bucks.
Here’s where it gets interesting: the difference in average premium costs between providers can be hundreds of dollars. But why settle for average when you can cherry-pick the best provider for your needs?
Top Auto Insurance Providers and Their Offerings
Let’s dive into the specifics. Below is a comparison of some of the top auto insurance providers in Massachusetts. This table highlights their coverage options, customer satisfaction, and average premium costs to give you a clear picture:
| Provider Name | Coverage Options | Customer Satisfaction Rating | Average Premium Cost |
|---|---|---|---|
| Progressive | Comprehensive, Collision, Liability | 4.5/5 | $1,200 |
| Geico | Liability, Uninsured Motorist, Personal Injury | 4.3/5 | $1,100 |
| Liberty Mutual | Collision, Roadside Assistance, Rental Reimbursement | 4.6/5 | $1,350 |
| Amica | Comprehensive, Gap Coverage, New Car Replacement | 4.8/5 | $1,300 |
Choosing between a well-known brand and a local company can be tough. Here is the deal: national providers like Geico and Progressive offer broad coverage and high-tech tools, BUT local companies often provide personalized service and may better understand regional claims trends.
Pro Tip: Always get quotes from at least three different providers to ensure you’re getting the best deal.
Well-known insurers often have brand trust and advanced digital tools. On the flip side, local companies can offer personalized customer service and flexibility in policy customization. Remember, the right fit depends on your priorities and driving habits.
Strategies to Lower Auto Insurance Costs
Think you’re paying too much for auto insurance in Massachusetts? You’re not alone. But, you can slash those costs with a few smart strategies.
Insurance premiums can weigh heavy on your wallet, but there are strategic steps you can take to keep those costs down. Let’s dive into how you can save big on your auto insurance.
Utilize Discounts and Bundling Options
One of the easiest ways to cut down your insurance costs is to tap into the discounts that insurers offer. In Massachusetts, insurers provide a variety of discounts ranging from safe driver discounts to multi-policy bundling.
- Safe Driver Discounts: Maintain a clean driving record and you could see significant savings.
- Multi-Vehicle Discounts: Insure more than one vehicle under the same policy to save more.
- Bundling Home and Auto: Combine your home and auto insurance with the same provider for a hefty discount.
Pro Tip: “Ask your insurer about lesser-known discounts. Many companies offer discounts for low annual mileage or for having specific safety features in your vehicle.”
Take a Defensive Driving Course
Did you know that completing a defensive driving course can lower your premium? Insurance companies love safe drivers, and Massachusetts is no exception. By taking a state-approved defensive driving course, you not only become a safer driver but could also score a discount on your policy.
Defensive driving courses teach you skills that reduce the risk of accidents, making you a lower insurance risk. Many insurers provide up to a 10% discount just for completing one of these courses. It’s a small investment with a big payoff.
Legal Aspects and Consumer Rights
Did you know that Massachusetts has some of the most stringent auto insurance laws in the country? These laws are designed to protect you as a consumer, but navigating them can feel like trying to decode a legal maze.
Here’s the deal: Understanding the legal framework and your rights can save you from headaches down the road. Let’s dive into what you need to know to stay on the right side of the law and keep your rights intact.
Massachusetts Auto Insurance Laws
Massachusetts requires that all drivers carry a minimum level of liability insurance. This includes coverage for bodily injury and property damage. BUT that’s just the start. It also requires coverage for Personal Injury Protection (PIP) and uninsured motorist protection. Your insurer is legally bound to offer these, so make sure you’re covered.
Consumer Rights in Auto Insurance
As a policyholder, you’ve got rights. Claims must be handled promptly and fairly, and you have the right to dispute any decisions. If your policy is canceled, you must be given adequate notice. Knowing these rights can give you leverage if you find yourself in a sticky situation.
Filing Complaints in Massachusetts
If you believe your insurer or agent has acted in bad faith, you have options. Step #1: Reach out to the Massachusetts Division of Insurance. Their website has a straightforward process for filing complaints. Step #2: Document everything. Your complaint will carry more weight with solid evidence.
Pro Tip: Always keep a detailed record of your communications with your insurance company. This can be invaluable if you need to file a complaint or pursue legal action.
Final Summary
And there you have it, folks! Whether you’re a seasoned driver or a newbie navigating the winding roads of Massachusetts, understanding your auto insurance options and costs is crucial. By choosing the right coverage and leveraging available discounts, you can cruise with peace of mind and maybe even save a few bucks for your next road trip. Safe driving!
Q&A
What are the minimum auto insurance coverage requirements in Massachusetts?
Massachusetts mandates a minimum coverage that includes bodily injury to others, personal injury protection, bodily injury caused by an uninsured auto, and damage to someone else’s property.
How do location and city affect auto insurance costs in Massachusetts?
Your city can significantly impact your rates. Urban areas like Boston may have higher premiums due to increased traffic and theft rates compared to rural regions.
Does age affect auto insurance premiums in Massachusetts?
Yes, younger drivers typically face higher premiums due to inexperience, while mature drivers often enjoy lower rates.
How can I lower my auto insurance costs in Massachusetts?
Consider bundling policies, maintaining a clean driving record, taking defensive driving courses, and exploring all available discounts from your provider.
What should I do if I have a dispute with my auto insurance company in Massachusetts?
You can file a complaint with the Massachusetts Division of Insurance, which oversees insurance industry practices in the state.
